Zydus Wellness is a branded consumer-health company that turns the logic of a pharmaceutical lab into everyday food, drink, and personal-care products - its original identity was built on creating categories rather than just entering them, starting with India’s first sugar substitute in 1991 and a pioneering skincare range even earlier. Over three decades, it grew from a pair of functional brands housed inside a pharma parent into a standalone listed business by bolting on acquisitions - a nutrition-drink and spreads portfolio from Heinz in 2019, a protein-snacking leader in 2025, and a UK-based digital vitamins platform in 2026 - each time buying a position it could then scale with its own distribution and R&D engine. The recurring approach is to own the number-one slot in a niche where the product itself does the convincing - a sweetener that tastes like sugar, a scrub that visibly peels, a protein bar that eats like a chocolate - and then stretch that brand into adjacent formats once the consumer trusts it.
Business segments
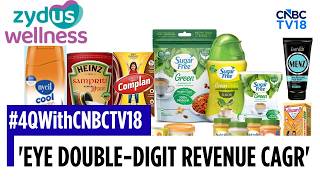
A single consumer-health platform expressed through six branded engines - three legacy category kings in glucose, sweeteners and skincare, two scaled food-and-nutrition platforms acquired and expanded, and a newly acquired digital VMS business in Europe - all pushed through one shared Indian distribution backbone.
1. Glucon-D: the summer-cash engine
A 90-year-old glucose powder that owns nearly three-fifths of its category and converts every Indian summer into a surge of replenishment demand - the business’s original and most weather-linked cash generator.
- The category leader by a wide margin - it holds a 58.9% value market share in the ₹1,035-crore glucose powder category, with more than 99% brand recall, so it is the default name consumers reach for when temperatures rise.
- Stretched into every format that fits the need - the core powder (Regular, Tangy Orange, Mango Blast, Nimbu Pani) has been extended into effervescent immunity tablets for kids, an oral rehydration solution, ready-to-drink electrolyte energy drinks, and a zero-caffeine drink mix, so the brand captures the same consumer across multiple consumption occasions.
- Seasonal dependency is the built-in risk - the brand’s performance is largely tied to the onset of a good summer, which means the business carries an annual weather bet that can be mitigated by having flexibility in its supply chain to manage the inventory.
2. Sugar Free: the category creator that refuses to share
India’s first sugar substitute, now holding a 96% market share, and systematically converting a niche diet product into a broader better-for-you pantry brand.
- Near-total ownership of the shelf - with a 96.1% value share of the ₹355-crore sugar-substitute category, the brand is effectively the market; competitors operate in the remaining sliver.
- Three molecules, three consumer jobs - Sugar Free Natura uses sucralose for everyday low-calorie sweetening, Sugar Free Green uses 100% stevia for the natural-seeking buyer (and has delivered 20 consecutive quarters of double-digit growth), and Sugar Free Gold+ moved from aspartame to sucralose-plus-chromium for blood-sugar management, so each variant pulls a distinct user without cannibalising the others.
- From sweetener to snack - the D’lite range extends the brand into chocolates, cookies, granola, and a choco spread, all carrying the zero/low-sugar promise, which moves the franchise from an ingredient sold in sachets to a branded food range with higher basket size.
- A bridge product for the mass market - I’m lite is a blended sugar (sugar plus stevia) that cuts calories by half while behaving like regular sugar, designed to pull mainstream households into the franchise without asking them to switch to a completely artificial sweetener.
3. Everyuth: the scrub-and-peel specialist
A skincare brand that does not fight the giant face-wash category head-on but instead dominates the two sub-segments where its pharmaceutical formulation heritage is most visible - scrubs and peel-off masks.
- Number one where the product is the proof - Everyuth Scrub holds a 48.6% share of the ₹405-crore facial scrub category, and Everyuth Peel-Off holds a 75.5% share of the ₹170-crore peel-off mask category; in the overall ₹4,695-crore facial cleansing market it is the number-five player with an 8.0% share in the MAT Mar 2026 period, so its strength is concentrated in the high-demonstration, high-repeat sub-categories.
- Functional claims backed by lab credentials - the range includes anti-pollution clay, charcoal, tan-removal lemon-and-cherry, and anti-acne formulations, all positioned as combining natural ingredients with scientific research, which is the same “pharma-to-consumer” language that built the parent group’s credibility.
- Extending into adjacent routines - the brand has added sheet masks, serums, night creams, and a newly launched Tan Removal Face Wash, so a consumer who enters through a scrub can stay within the brand for her full regimen.
4. Complan and Nutralite: the acquired nutrition platform
Two brands bought together in the 2019 Heinz India deal - a legacy milk-nutrition drink and India’s leading cholesterol-free spread - that together give the company a year-round food-and-nutrition anchor to balance its seasonal and niche portfolios.
- Complan: a trusted name repositioned for growth - with 90% brand recall and a 4.0% share of the ₹6,575-crore nutrition-drink category, it is the number-four player; the company has split the franchise into Complan NutriGro for kids (taller growth, chocolate format) and Complan VieMax for adults (gut wellness with prebiotic and probiotic, marketed through doctor detailing), so the brand now addresses the 18-20% of the category that is adult nutrition rather than fighting only in the crowded children’s segment.
- Nutralite: the fat-spread leader that outgrew spreads - it holds the number-one position in fat spreads and has expanded into mayonnaise, chocolate spreads, peanut butter, and a dairy range under Nutralite DoodhShakti (pure ghee, cow ghee, butter), while Nutralite Professional supplies institutional kitchens from small dhabas to five-star hotels, so the brand captures both household and food-service demand from the same manufacturing base.
- Consistent growth despite input headwinds - the brand delivers double-digit growth even when gas supply disruptions hit operations, suggesting the demand pull is strong enough to absorb supply-side friction.
5. RiteBite Max Protein: the protein-snacking bet
A recent acquisition that made Zydus Wellness the number-one player in protein bars, cookies, and chips overnight - a small but fast-moving category where the product doubles as a lifestyle statement.
- Bought, not built - acquired through the purchase of Naturell (India) in October 2024, the brand had been operating in healthy snacks since 2007 and already held the top slot in nutrition and protein bars and in protein cookies and chips, so Zydus bought category leadership rather than spending years trying to dislodge an incumbent.
- Rapid format expansion - in its first year under Zydus, the brand entered four new categories: millet-wafer protein bars, a ready-to-drink protein beverage, a ghee-jaggery bar, and Korean-flavoured chips, which stretches the protein platform from bars into beverages and ethnic snacks.
- Quick-commerce fit - the brand saw robust growth on quick-commerce platforms, and one year post acquisition its EBITDA moved from breakeven to approaching double-digit margins, suggesting the unit economics improve fast once the distribution footprint expands.
6. Comfort Click: the digital VMS entry into Europe
A UK-based, e-commerce-first vitamins and supplements platform acquired in mid-2025 - a separate geography, channel, and category from the Indian business, run independently and funded through a low-cost bridge loan.
- A fast-growing asset in a large market - Comfort Click generated GBP 134 million in revenue in the year to June 2025, with a five-year CAGR of 52%, operating in a European VMS market estimated at around GBP 11 billion; it was recognised by the Financial Times as one of Europe’s fastest-growing companies for the third consecutive year.
- Three brands, three consumer sets - WeightWorld covers adult plant-based supplements, vitamins, minerals, and sports nutrition; maxmedix is a paediatric gummy VMS brand; and Animigo is a natural pet VMS brand, so the platform spans human and pet health without brand overlap.
- Marketplace-first, now adding retail - the majority of CCL revenue comes through e-commerce and direct-to-consumer channels in the UK and Europe, with recent launches on Boots.com and on Amazon in the UAE, which adds a wholesale and retail leg to what was a purely digital model.
- Acquisition funded with external debt, not Indian cash flows - the GBP 239 million purchase was financed through a low-cost bridge loan in GBP, subsequently refinanced into a Euro facility, so the Indian balance sheet was not drained to fund the overseas move.
The shared Indian go-to-market engine
A distribution network reaching 2.8 million stores through 1,950-plus distributors and 2,700 feet-on-street representatives, with a deliberate shift toward direct relationships with modern trade and e-commerce chains - every brand in the portfolio rides this same infrastructure.
- Milk procurement is vertically integrated - for the Nutralite dairy range and Complan, the company collects 400,000 litres of milk daily through 36 collection centres around Aligarh, working directly with 25,000 farmers, which gives it control over quality and cost for its single most important fresh input.
- Organised channels are rising fast - modern trade and e-commerce together reached 30% of domestic sales in FY26 (up from 24% the year before), with quick commerce alone at 7-8% of total business and 44-45% of e-commerce; the company switched from a distributor-led model to direct supply for these chains, cutting out a layer to improve availability and save margin.
- R&D as the product factory - a dedicated Ahmedabad centre staffed with PhDs and post-doctorates (20% of the team holds a doctorate) works with academic institutions in India and abroad; twelve new products were launched in FY25, and as of August 2021, new products launched in the preceding 36 months had contributed almost 5% of total revenue, so the pipeline is active but still a small portion of the base.
Group structure and partners
Zydus Wellness is a publicly listed company majority-held by its pharma parent, with a growing web of international subsidiaries created to hold specific acquisitions and market-entry vehicles - the structure mirrors the step-by-step expansion of the brand portfolio.
- Promoter control with public float - Zydus Lifesciences Limited held 57.59% as of FY25, and the broader promoter group held 57.5% a year earlier, with over 80,000 shareholders making up the rest.
- Indian operating subsidiary - Zydus Wellness Products Limited is the wholly owned subsidiary that runs the core domestic business operations.
- International holding structure - Zydus Wellness International DMCC in Dubai (incorporated 2019) manages the majority of international operations and has recently set up new subsidiaries in Ireland and Dubai for food, nutrition, and nutraceutical expansion.
- Comfort Click sits under a UK chain - Alidac UK Limited was incorporated in August 2025 as a wholly owned subsidiary, and through it Zydus acquired 100% of Comfort Click Limited, which itself has subsidiaries in India, Ireland, and the USA.
 10:04
 12:02